Commercial Insurance

General Liability Insurance for Everyday Business Risk

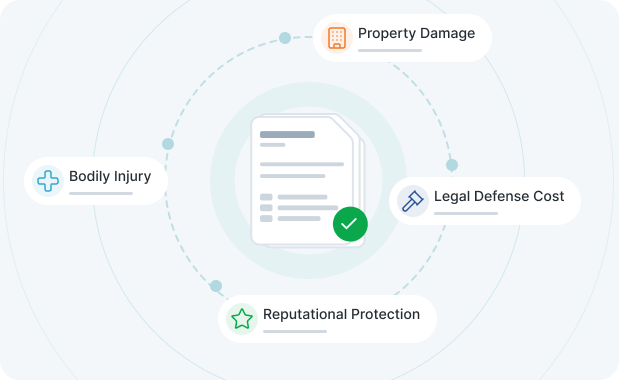
General liability insurance, also known as business liability or commercial general liability insurance, protects businesses from claims involving bodily injury, property damage, and reputational harm.
Request Demo
Overview

General Liability Insurance Overview

General liability insurance provides financial protection when a business is held responsible for injury, damage, or loss experienced by a third party.
It plays a foundational role in business risk management by covering common incidents that can result in medical expenses, legal fees, and reputational impact.
Did you know?
According to Forbes, a slip and fall claim costs an average of $20,000, with legal costs often starting in the tens of thousands and increasing significantly depending on the case.
Coverage

Core Coverages in a General Liability Policy

A standard General Liability includes core coverages:

Bodily Injury Coverage

Covers medical expenses when a third party is injured on business premises or as a result of business operations.

Reputational Harm Protection

Helps address financial losses caused by negative publicity or damage to brand perception.

Property Damage Coverage

Covers the cost of repairing or replacing a third party’s property that is damaged by the business or its employees.

Advertising Injury Protection

Provides coverage if business advertising activities result in financial harm to another party.

Copyright Infringement Coverage

Covers legal expenses if the business is accused of using protected content without proper authorization.

Summary Coverage Scope

At its core, general liability insurance helps cover medical and legal expenses resulting from covered incidents.

Coverage Limits

Coverage Limits and Policy Structure

General liability policies are structured around occurrence limits and aggregate limits.

Key Cost Indicators:

Defines the maximum amount the insurer will pay for a single claim during the policy period.
Defines the total amount the insurer will pay for all claims combined within the policy term, typically one year.

Considerations

Selecting appropriate coverage limits requires evaluating:
Business Activities That Increase Exposure
On-Site Service Operations
Physical Business Locations
Marketing and Advertising Activities
A policy structured as $1M / $2M provides $1 million per claim and $2 million total coverage across all claims.
Built For

Businesses That Benefit from Liability Coverage

General liability insurance applies across a wide range of industries and business sizes.
It is commonly used by businesses that:

Businesses with storefronts, offices, or facilities where customers, vendors, or partners are present.

Operations that rely on physical assets which could be damaged or cause damage during use.

Businesses that regularly engage with clients, increasing exposure to injury or liability claims.

Any business where routine activities carry the risk of accidental damage, injury, or disputes.

Typical examples include:

Customer-facing environments with regular foot traffic and in-store interactions.

High-contact environments with operational and premises-related risks.

On-site work that introduces exposure to property damage or third-party injury.

Offices and service-based businesses with client interaction and reputational exposure.

Improving General Liability Workflows with Savus

Managing general liability policies often involves manual processes, fragmented data, and inconsistent underwriting requirements.
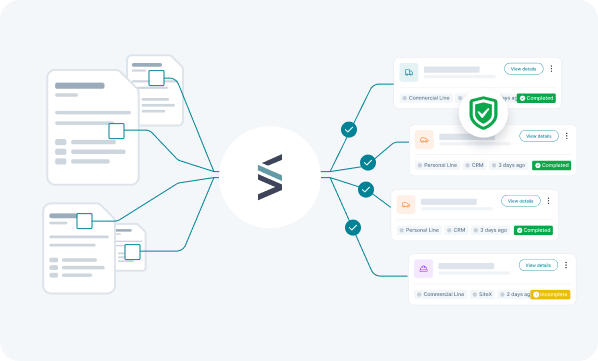
Savus addresses this by automating key steps in the workflow:

Single-entry submissions across multiple carriers

Real-time validation against carrier rules

Reduced manual errors and rework

Faster quote turnaround and improved bind rates

By streamlining the process, agencies can focus less on administration and more on closing business.

Strengthen General Liability Protection with Smarter Workflows

Deliver accurate quotes faster, reduce operational friction, and improve conversion across your book of business.